Vail’s Swiss Expansion Faces a Returns Question
Vail’s Swiss deals face scrutiny over returns. Local accounts reveal part of the picture, but comparison with the original targets remains incomplete.
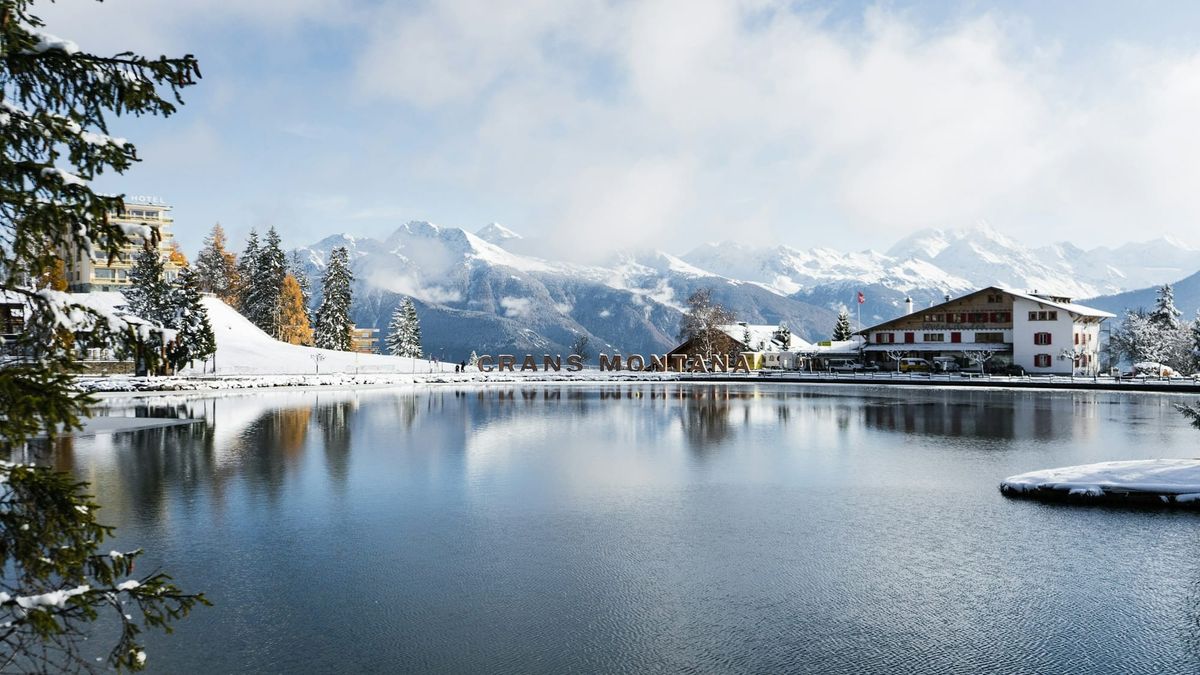
Vail Resorts’ expansion into Switzerland is facing a question that extends beyond its contested board election: can shareholders establish whether Andermatt-Sedrun and Crans-Montana are delivering the returns originally anticipated?
Gregory S. Meyer, an independent board candidate separate from Oasis Management, raises that challenge in his preliminary proxy dated 30 October. Our coverage of the wider board contest explains the election backdrop. His Swiss argument deserves separate scrutiny—but the available evidence is more nuanced than an absence of results.
In March 2022, Vail forecast more than CHF5m in earnings before interest, tax, depreciation and amortisation—EBITDA—from Andermatt-Sedrun in FY2024. Its longer-term ambition exceeded CHF20m annually within five to seven years, conditional on investment approvals and completion, and including incremental Epic Pass sales. That was a development forecast, not an immediate earnings commitment.
For Crans-Montana, announced in November 2023, Vail expected approximately CHF5m EBITDA in FY2025. Annual earnings were expected to exceed CHF15m after approximately CHF30m of planned investment, again including additional Epic Pass sales. These wider network benefits matter: earnings generated by making a global pass more attractive need not appear entirely in a Swiss operating company’s accounts.
The transaction structures also resist a simple combined price tag. Andermatt’s announced CHF149m investment bought a 55% interest: CHF110m went into the mountain company for improvements and CHF39m to Andermatt Swiss Alps for reinvestment in surrounding property development. Vail did not buy the entire village development business. Crans-Montana’s CHF118.5m headline valuation included approximately CHF7m of debt; Vail subsequently reported an adjusted purchase price of CHF97.2m. Adding the two headline figures would mix investment funding with enterprise valuation.
Vail acquired approximately 84% of Crans-Montana’s lift company. Its subsequent annual report records full ownership of the associated SportLife ski school and 11 restaurants, rather than the 80% ski-school stake initially announced. These are mountain and related operating businesses, not ownership of the destination’s accommodation market.
Subsequent group disclosures provide fragments. Crans-Montana reduced FY2024 Resort Reported EBITDA by US$11.1m, but US$7.9m comprised acquisition, closing and integration costs; the remaining US$3.2m operating loss covered the post-acquisition fourth quarter. It cannot fairly be compared with a normal full winter. FY2025 brought US$15.4m of incremental non-pass lift revenue, which establishes revenue contribution, not profitability.
There is, however, public Swiss financial information. Andermatt-Sedrun Sport’s 2025/26 annual report records EBITDA of CHF6.31m, compared with CHF4.58m the previous year. That is meaningful operating progress. It does not establish whether the FY2024 target was achieved, or reconcile local accounting with Vail’s forecast basis and network-wide pass benefits.
The group’s FY2026 reporting does not provide that reconciliation. Vail’s 30 October shareholder letter defends its integrated network and challenges dissident candidates’ qualifications; Uchi found no published response specifically resolving Meyer’s Swiss returns questions. That absence does not substantiate his criticism.
For property owners, the investment logic remains relevant. Better lifts, snowmaking and dining can strengthen the visitor experience; more accommodation can support longer stays; international pass distribution can introduce new customers. Each is intended to reinforce the others. But mountain EBITDA is neither a rental yield nor a property-price forecast: accommodation supply, occupancy, room rates and ownership costs still determine local outcomes.
The useful next disclosure would reconcile each resort’s annual EBITDA with its original forecast, separating local operations, incremental pass benefits and exceptional costs, alongside capital actually spent and the remaining investment timetable. That would turn a contested argument into an assessable investment record.