Vail Bets on Returning Skiers as Advance Pass Sales Fall
America's Vail Resorts is forecasting a recovery despite weaker advance pass sales. Its latest results and earnings call show why returning visitors matter to the wider resort economy.
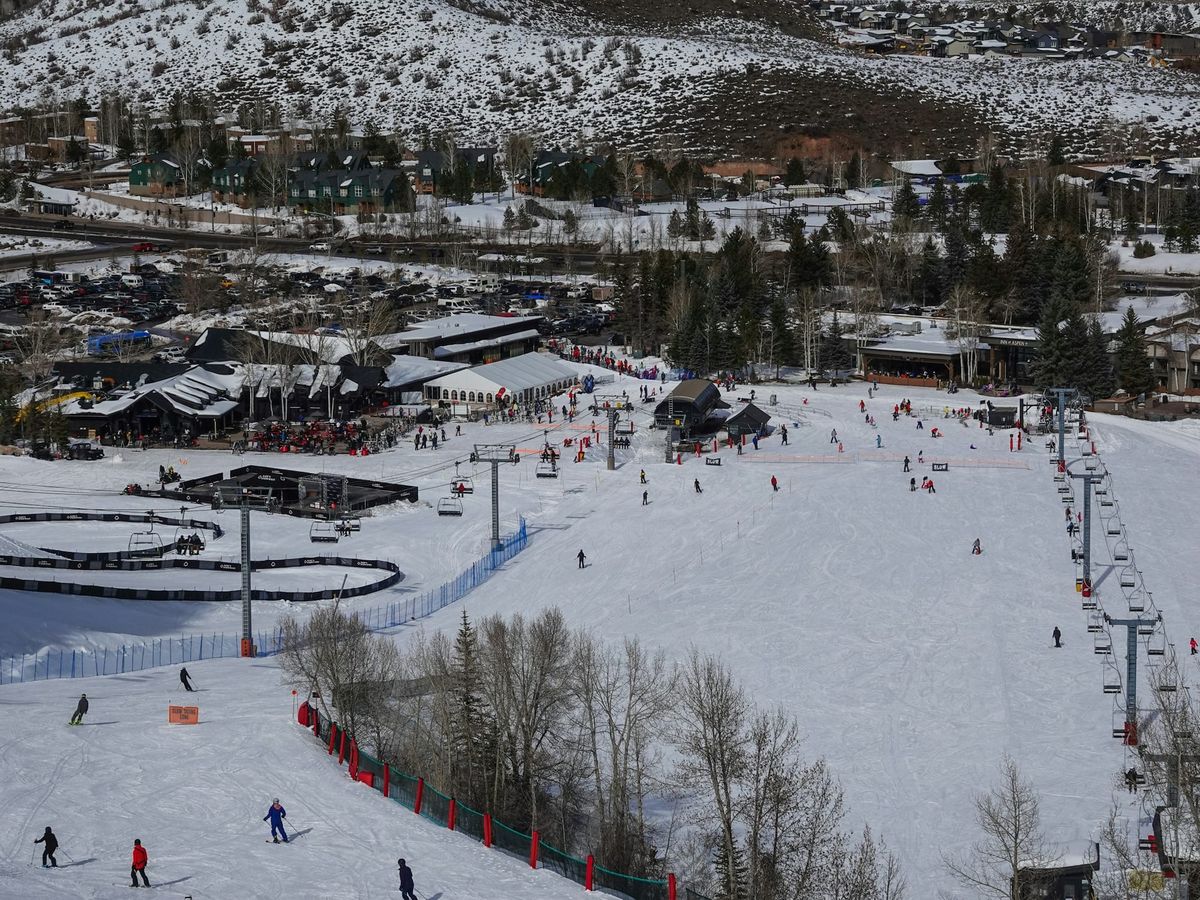
America's Vail Resorts is forecasting a recovery after a difficult winter, despite fewer skiers committing to its next season in advance. For the mountain destinations around its resorts, the question is how many of those hesitant customers will eventually travel—and what they will spend when they arrive. The latest results provide a useful test of the relationship between the financial resilience of a resort operator and the accommodation economy surrounding it.
The company reported on 28 September that North American pass sales for 2026/27 were down 12% in units and 6% in dollars through 18 September, against the comparable prior-year period. Weakness was concentrated in passes used by destination visitors who ski less frequently. Management believes some customers are delaying their decisions after last winter’s poor conditions, leaving an opportunity to recover demand later.
A Recovery That Still Requires Visitors
Vail’s FY2026 Resort Reported EBITDA fell 11.7% to US$745.7 million. Its FY2027 forecast of US$805 million–865 million assumes normal weather. During the earnings call, finance chief Angela Korch clarified that guidance does not depend on an improvement in the remaining pass-selling period: Vail expects to recover a meaningful share of the missing pass visits through lift-ticket purchases.
That is a plausible route to recovery, but it remains a forecast. A decision to defer buying a pass can eventually become a later ski holiday, a shorter trip or no trip at all. Accommodation operators therefore need to examine booking pace and achievable room rates alongside the pass figures, particularly where a destination relies on guests arranging flights and several nights away. A lower advance commitment makes those operating assumptions harder to settle before winter begins.
Last season illustrates the distinction. Vail’s total skier visits fell 13.4%, while lift revenue declined only 3.5%. Combined revenue per available room at its owned hotels and managed condominiums fell 6.3%. Those accommodation figures cover Vail’s own reported portfolio; they do not establish a corresponding decline across every resort market or in property values.
The Call Left the Board Contest Unresolved
Oasis Management’s campaign remains relevant. Its 22 September ownership amendment disclosed a 7.4% stake*, while its four proposed directors remain nominees. Katz said Vail would not answer questions about board nominations while the evaluation continued. No Oasis representative was identified among the Q&A participants, and the call contained no announcement of a resort sale or settlement.
The new SEC amendment reports 3,222,085 shares, an increase of 599,523 from the previous disclosure. It updates ownership and acquisition funding without announcing new strategic demands, a settlement or a sale. Its triggering event is dated 25 September, so we should not describe this as a reaction to the reported results.
There was, however, a substantive portfolio question. Asked whether Australia might become non-core after difficult seasons, Katz defended its place in the network, including its ability to bring Australian passholders to North America. That sets out management’s current strategic position; it does not settle the activist debate or rule out future changes.
What the Resort Economy Should Watch
For Uchi Insights readers, the commercial issue extends beyond who owns a mountain. A hotel or holiday-home business needs to understand whether its resort attracts visitors who stay locally, how sensitive those guests are to the total cost of a trip, and whether access and service improvements give them a reason to return. The same questions are useful in Japan, although Vail’s results provide no evidence that customers are switching to Japanese destinations.
The next test is whether later purchases translate into visits and occupied rooms. Resort owners can strengthen distribution and improve the guest experience, but surrounding property businesses must still assess their own demand. Any material Oasis response would add a separate governance development; the operating challenge is already clear enough to examine on its own.
We hope you enjoyed this free article. Uchi Insights provides the latest market news from across Japan as well as global mountain resorts, most of it for free.
But we'd love a little love!
If you want the latest data and deep-dive reports, you can access premium Uchi Insights covering pricing, sales, supply and market trends across Japan’s leading resort real estate destinations.
Twelve months of Premium access costs US$200—roughly the price of a good pair of gloves for that Japanese powder snow.
If you are buying, selling, investing or simply trying to understand where Japan’s resort property markets are moving, make sure you have the same data and analysis at your fingertips.
Don’t be the one wondering what everyone else knows.
Sources
- Vail Resorts — FY2026 results and FY2027 outlook, 28 September 2026
- Benzinga — Complete FY2026 earnings-call transcript, 28 September 2026
- MarketBeat — FY2026 earnings-call transcript with timestamps
- SEC — Oasis Schedule 13D amendment, signed 22 September 2026
- Vail Resorts — Board nomination update, 11 September 2026