Ski Branded Residences Are Growing Through Smaller Schemes
The ski branded-residence pipeline adds projects faster than homes. Our calculations examine scheme size and what buyers need to know about shared costs.
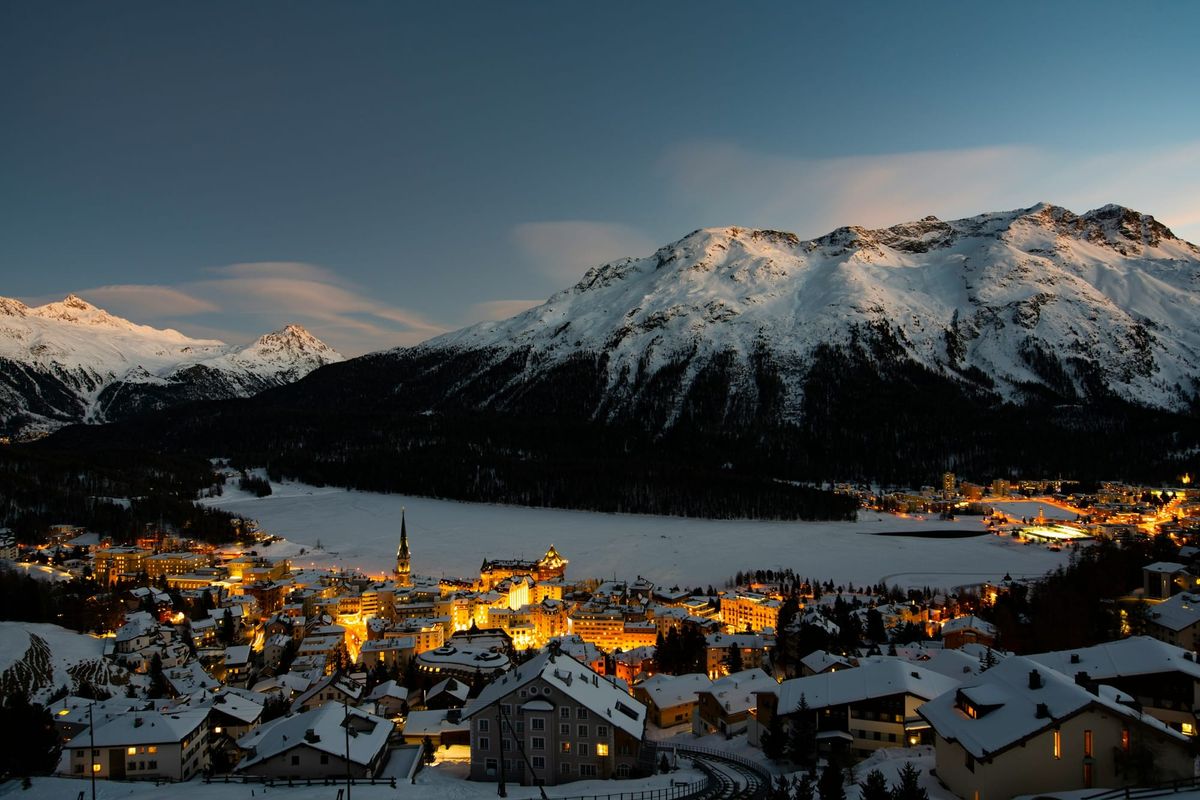
Across mountain markets in the United States, Switzerland and other ski destinations, branded residences are expanding through a pipeline that is smaller per development than the completed stock. Savills’ new 2026/27 Ski Report identifies about 3,700 existing residences across forty schemes, with another 790 units in fifteen projects expected by 2031. Those figures describe a development pipeline, not guaranteed completions or sales.
The distinction between projects and homes is commercially useful. Fifteen additional schemes would increase the number of developments by more than a third, but the additional residences amount to just over a fifth of the existing unit count. A growing number of brand names on a resort map can therefore overstate the growth in accommodation or residential supply.
Uchi’s calculation from the published figures also raises a question for buyers: when a development becomes smaller, how are the costs of its services spread? The answer depends on the operating agreement and the wider hotel business, rather than the brand alone.
Follow the mountains beyond the snowfall. Unlock this article and the Premium Analysis archive, with new premium articles delivered straight to your inbox.
Join for US$80 a year–roughly a coffee a month to keep yourself informed.