KDX’s Two Hotel Purchases Show How Public Capital Prices Tourism Risk
KDX paid ¥18.057bn for two variable-rent hotels. Our transparent analysis calculates price per room, implied appraisal NOI and the risk behind the yield gap.
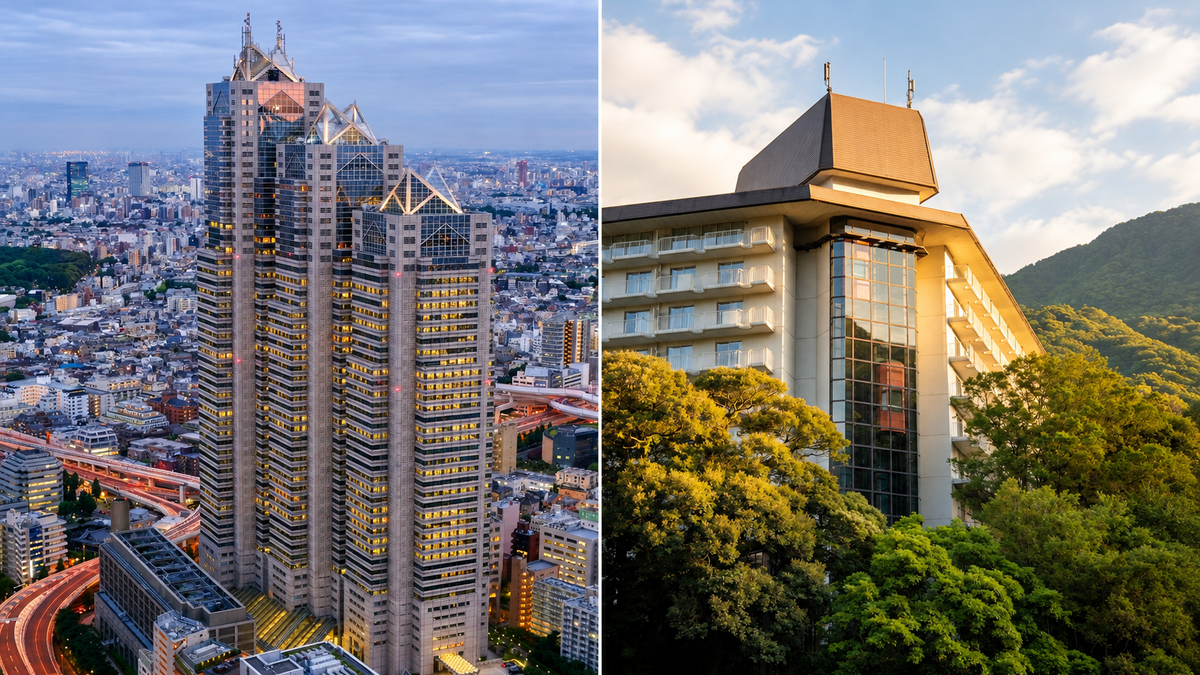
KDX Realty Investment Corporation’s purchase of two hotels offers an unusually clear public view of how institutional capital is pricing different Japanese tourism assets. The REIT agreed to pay ¥12.0 billion for the 216-room ibis Styles Tokyo Bay and ¥6.057 billion for the 105-room BEB5 Okinawa Seragaki. Both were acquired on 1 October under leases with rent that varies with hotel performance.
The disclosed appraisal NOI yields are 4.7% for the Tokyo Bay hotel and 6.22% for the Okinawa resort. Weighted by acquisition price, the two properties imply an appraisal NOI yield of about 5.21%. The gap is not proof that one is better value. It is a prompt to examine location, operator, asset age, income volatility and the assumptions embedded in each appraisal.
This article uses the REIT’s disclosure to calculate price per room, compare the two yields and explain what variable rent transfers—and does not transfer—between owner and operator. It also places the hotels inside KDX’s wider seven-property acquisition and one-property disposal, showing why hospitality can look attractive within a diversified portfolio when inflation and tourism support revenue growth. The calculations are transparent and reproducible; they are not proprietary performance data.
Understand the market around the mountain.
Follow our coverage of Japan and global mountain destinations, then explore our membership options for detailed property data and market reports on Japan’s resort markets.
Your free article continues below.