Japan’s August Visitor Decline Conceals a Changing Market Mix
August arrivals to Japan fell 9.6%, but several source markets grew strongly. Japan’s hotels need to look beyond the national total when assessing demand.
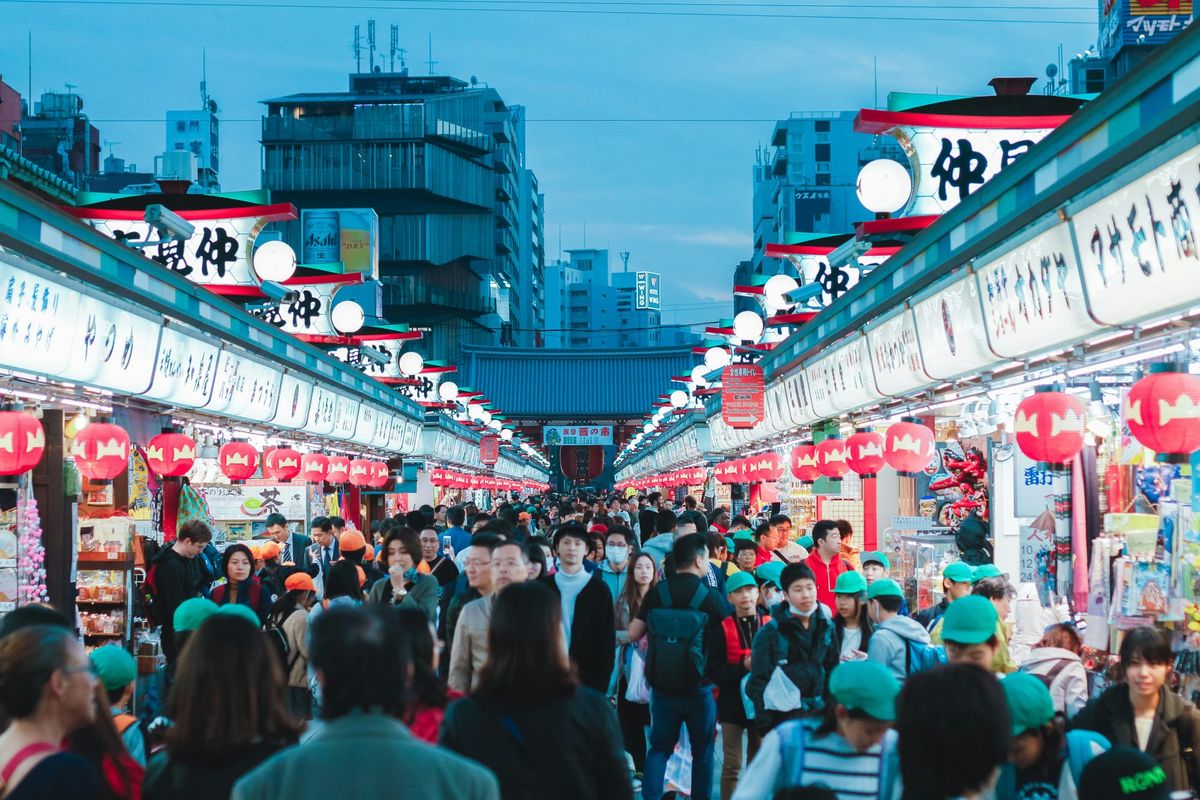
Japan recorded fewer international visitor arrivals in August than a year earlier, but the national decline gives an incomplete picture of demand. The latest Japan National Tourism Organization estimates show a sharp divergence between source markets, a distinction that matters for hotels deciding how to price rooms and where to focus their marketing before winter.
Figures published on 16 September put August arrivals at 3,098,900, down 9.6% from August 2025. The January–August total reached 27,626,300, a decline of 2.7%. These are preliminary estimates of inbound visits, rather than a count of unique people travelling during the year. They also cover more than leisure tourists and should not be read as hotel bookings or overnight stays.
China accounts for much of the weakness in the monthly comparison. Arrivals from that market fell 59.0% to 418,000. South Korea moved in the opposite direction, rising 28.7% to 850,500, while Taiwan increased 7.3% to 666,000. US arrivals grew 1.5% to 197,400. Travel Voice’s Japanese-language report notes that 14 markets achieved records for an August, despite the lower national total.
That combination makes a broad description of Japan as either booming or slowing particularly unhelpful for an individual accommodation business. A hotel’s exposure depends on its own guests, their booking channels and the reasons they visit. Two properties in the same destination could experience quite different trading conditions even if the number of available rooms and local attractions remained unchanged.
Nor does the August release settle the outlook for the ski season. Summer travel patterns cannot establish how many visitors will book a February chalet. National arrivals do not identify nights spent in a particular mountain town, and a change in short urban visits may have little direct bearing on a resort’s longer stays. Winter forecasts still require forward reservations and reliable information about the markets those bookings represent.
There is nevertheless an immediate use for the data. Operators can compare the source-market movements with their own booking pace and cancellation patterns. If their performance diverges sharply from the national picture, that is a reason to investigate distribution or destination demand before changing prices. Discounting every room in response to a weaker headline would assume a uniformity that the figures do not show.
For property owners, the release is also a reminder to ask what sits behind an occupancy forecast. An assumption based solely on continued growth in total arrivals is less informative than one explaining the expected guest mix and length of stay. August’s figures give that discussion a firmer starting point, while leaving local performance to be demonstrated.
We hope you enjoyed this free article. Uchi Insights provides the latest market news from across Japan as well as global mountain resorts, most of it for free.
But we'd love a little love!
If you want the latest data and deep-dive reports, you can access premium Uchi Insights covering pricing, sales, supply and market trends across Japan’s leading resort real estate destinations.
Twelve months of Premium access costs US$200—roughly the price of a good pair of gloves for that Japanese powder snow.
If you are buying, selling, investing or simply trying to understand where Japan’s resort property markets are moving, make sure you have the same data and analysis at your fingertips.
Don’t be the one wondering what everyone else knows.
Sources
- JNTO: August 2026 Visitor Arrivals, Preliminary Market Table, 16 September 2026
- Travel Voice: Japanese Reporting on August Arrivals, 16 September 2026